Austin has long stood at the forefront of America’s housing crisis, but now another city, starkly different from the Texas capital, is facing similar challenges.
Over recent years, Austin’s real estate market has been hit hard by declining prices, an exodus of residents, and a surplus of homes. These factors have combined to create a significant downturn in the market.
The trouble began brewing after Austin experienced a substantial housing boom during and following the pandemic. As lockdowns and remote work became widespread, individuals from high-tax, congested liberal cities flocked to Austin, drawn by its space, sunshine, and perceived affordability.
However, many of these newcomers soon discovered that Austin wasn’t the ideal fit they had imagined. This led to a reverse migration, leaving behind a city where many locals were already feeling the squeeze of rising property prices during the boom.
Meanwhile, developers had ramped up construction of new homes and condos to cater to the heightened demand during the pandemic. Now, they find themselves facing a market where that demand has all but vanished.
At the same time, builders had developed plenty of new homes and condos to meet the surge in pandemic-era demand, only to face the reality that that demand had not only dwindled, but practically disappeared.
This perfect storm helped explain why the city topped lists for fastest falling prices, highest inventory, and most residents fleeing. But the new city that has now overtaken Austin in the most important measure – falling prices – has not faced any of these same issues.
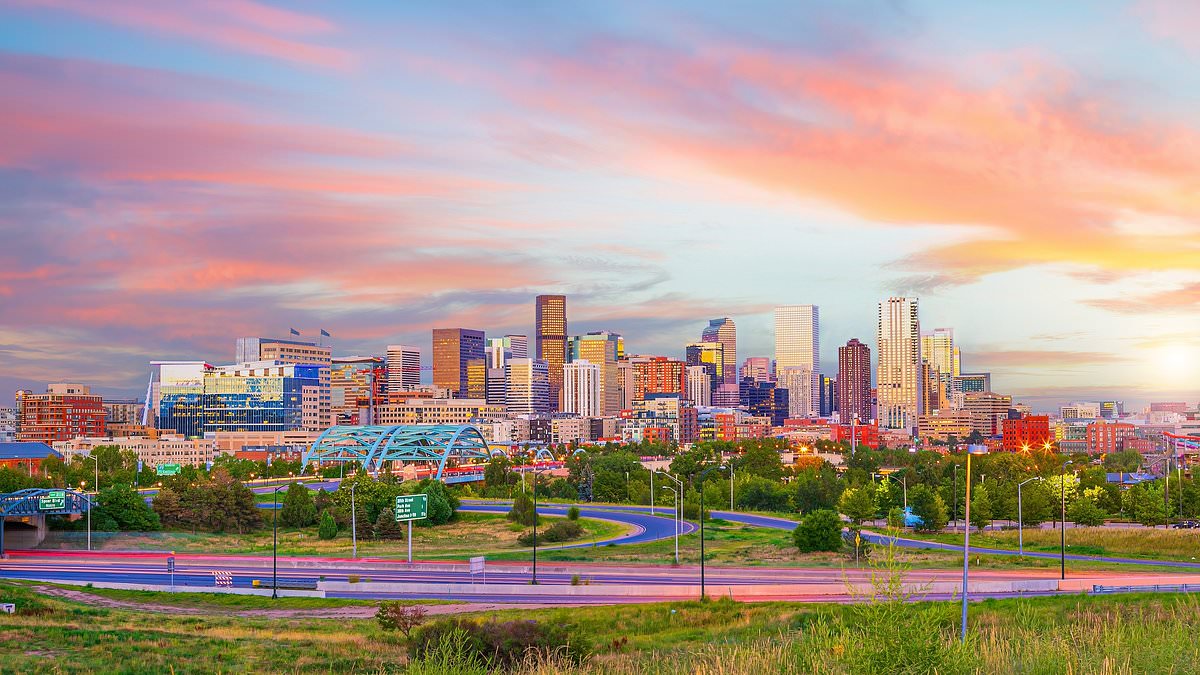
Denver, Colorado, is now seeing home values drop at the fastest rate in the entire country.

Austin’s housing market has been the epicenter of America’s housing crisis for some time now

Denver, Colorado, is now seeing home values drop at the fastest rate in the entire country
Prices in the mountainous Western city have fallen 2.2 percent on average year-over-year, according to data from the S&P Cotality Case-Shiller Index.
While Denver did not experience quite the pandemic boom seen in Sun Belt cities like Austin, Tampa, and Phoenix, it did undergo its own surge in inventory last spring. Because of this, experts have long been forecasting a property price decline.
According to Realtor.com, the median listing price for a home in Denver currently sits at around $545,000, with a year-over-year change of more than -5 percent and a three-year change of a staggering -14 percent. These figures differ from the decline reported by the S&P, as that index tracks home values rather than listing prices.
Local real estate agents attribute the decline to several factors, including a slowdown in migration to Colorado from other states, rising insurance costs, and weaker demand for condos and townhomes, which make up a disproportionately large share of Denver’s housing market.
At the same time, the strongest housing markets remain concentrated in the Northeast and Midwest. Chicago leads all major metro areas with 5.0 percent annual growth, followed by New York at 4.7 percent and Cleveland at 4.2 percent.
‘The 7.2 percentage point spread between Chicago and Denver illustrates how localized the housing story has become,’ says Nicholas Godec, head of fixed income tradables and commodities at S&P Dow Jones Indices.
While there are some winners, there are more losers, with more than half of major US metros posting year-over-year home price declines.
‘More than half of major US metropolitan markets posted year-over-year price declines in February, signaling that the housing slowdown has broadened well beyond its Sun Belt origins,’ says Godec. ‘The geographic mix has shifted meaningfully.’

While Denver did not experience quite the pandemic boom seen in Sun Belt cities like Austin, Tampa, and Phoenix, it did undergo its own surge in inventory last spring

Local real estate agents attribute the decline to several factors, including a slowdown in migration to Colorado from other states

Nicholas Godec, head of fixed income tradables and commodities at S&P Dow Jones Indices
Beyond plummeting prices, most metros in the US now fall firmly into buyer’s market territory – meaning there is more supply than demand, and house-hunters hold all the power.
As of early April. there are 46.3 percent more sellers than buyers nationwide, the widest gap on record and a clear sign the market has tipped decisively in buyers’ favor.
The last time conditions were this favorable to buyers was during the 2008 housing crash, when demand collapsed and inventory flooded the market.
Now, while the causes are different, the effect is similar: too many homes, not enough buyers – and growing pressure on prices.
On a local level, the imbalance is even starker. Just five metro areas remain seller’s markets – all of which are located in the Midwest and East.
Newark, NJ, is the strongest seller’s market, with buyers outnumbering sellers by around 31 percent.
New Brunswick, NJ, Nassau County, NY, Montgomery County, PA, and Milwaukee, WI have also managed to cling to seller-friendly conditions.