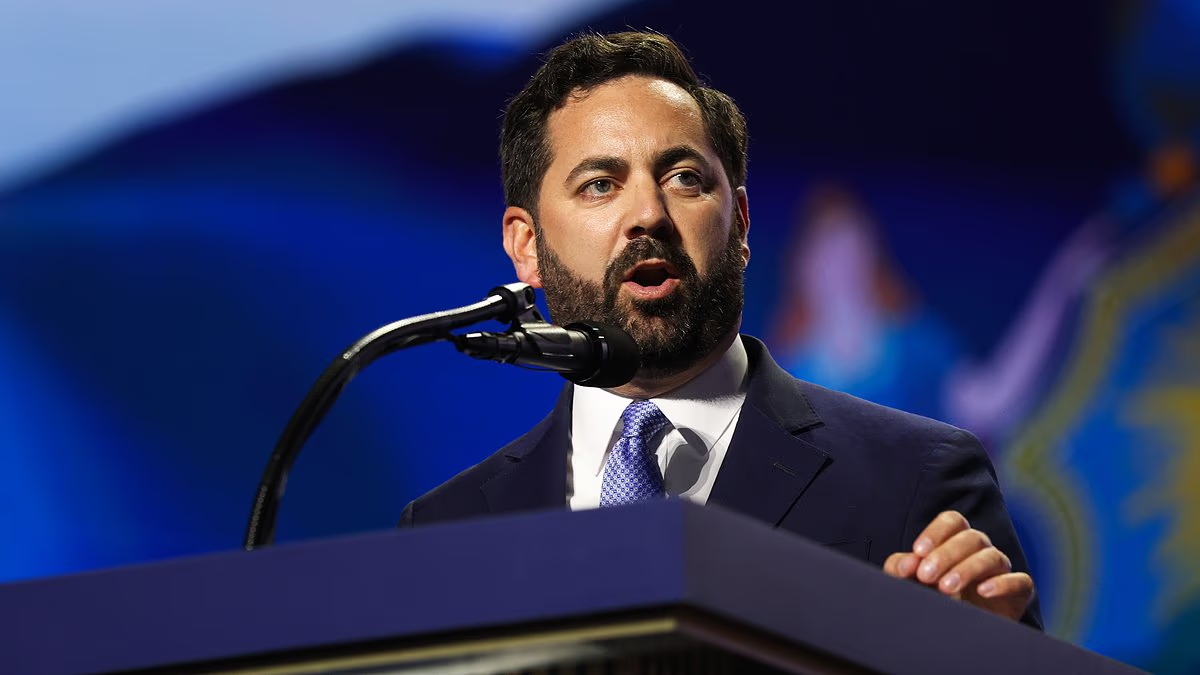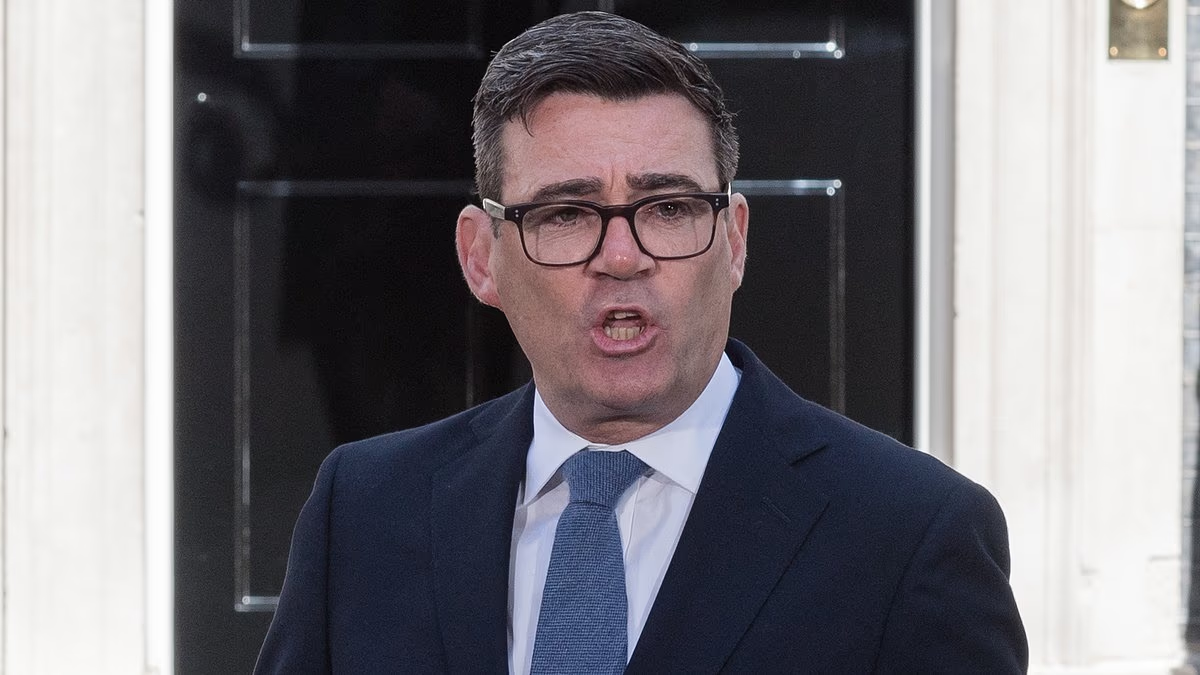

The Government is carrying a vast and growing debt burden, owing almost £3 trillion to lenders. This financial year alone, Chancellor John Healey is expected to raise about £115 billion through borrowing—roughly two and a half times the amount sought by the Exchequer a decade ago.
That money is raised through the gilts market. Government loans are packaged into bonds and sold to investors ranging from major financial institutions to private savers. The name comes from the original paper certificates, which were edged in gold. Today, gilts can mature anywhere from a few months to 50 years or longer.
Most gilts are issued at £100, known as their par value, and pay interest—called the coupon—twice a year.
The UK Government has never defaulted on a gilt, making the bonds among the safest investments available. Even so, major investors are becoming increasingly concerned about the scale of current borrowing and the sums the Government may need to raise in the years ahead.
Prime Minister Andy Burnham is untested and has made a series of bold promises. At the same time, geopolitical tensions are putting pressure on defence spending, while inflation is pushing up costs across the economy—including for government departments.
The result is growing unease. In financial markets, nervous investors typically demand a higher return before committing their money. Current borrowing costs show just how sharply that appetite has changed.
Five years ago, the Government paid less than 1 per cent a year to borrow for 30 years. Today, the rate has climbed above 5.9 per cent, its highest level since 1998. Ten-year borrowing now costs the Exchequer about 5.3 per cent—more than it did during the global financial crisis.

The UK Government has never failed to repay a gilt, so these bonds are largely considered safe investments. Now, under new PM Andy Burnham, it looks like borrowing is set to rise
For Healey and his team, higher yields create a raft of problems. For investors, however, they present an attractive opportunity: government-backed bonds offering unusually high returns, with a wide range available through brokers and online platforms including AJ Bell, Hargreaves Lansdown and Interactive Investor.
Yet the gilt market is not straightforward. Although a gilt’s coupon is fixed from the day it is issued until maturity, the bond itself is traded daily, much like a share. Its market price moves as demand from investors changes.
Those price movements alter the yield, which is calculated by dividing the coupon by the bond’s price and expressing the result as a percentage. When yields rise, prices fall; when yields fall, prices rise.
Consider a gilt issued in 2025 and due to mature in 2056. It pays annual interest of 5.375 per cent—a generous coupon a year ago, but one that no longer satisfies investors. Their demand for a higher return has pushed the price down to £92.60, lifting the annual yield to just over 5.8 per cent. That is appealing in its own right, but the bond also benefits from an important tax advantage: gilts are exempt from capital gains tax.
Someone buying this gilt today would pay £93.80 and receive £100 when it matures in 30 years, creating a substantial gain that is entirely tax-free. Once that uplift is included, the gilt’s gross yield rises above 5.9 per cent—an attractive return given that the borrower is the Government.
Investors can keep gilts until maturity, or sell them at any point before then. However, prices could fall further if market sentiment towards the UK economy deteriorates. Conversely, a surprise success for Healey at next month’s Budget could improve confidence in the Government and push prices higher.
While the high interest payments are tempting, the tax treatment of gilts is often the biggest attraction for investors.

Chancellor John Healey is expected to borrow around £115 billion, two and a half times the amount the Exchequer sought out just a decade ago
The Government issued huge quantities of gilts during the Covid years, when bank rates were close to zero and bond coupons were only marginally higher. As a result, the market is now awash with gilts paying coupons of 0.5 per cent or less. Many trade at substantial discounts to their original issue prices.
Ryan Hughes of AJ Bell says: ‘Short-dated gilts for higher-rate taxpayers look pretty appealing and there are some really high rates on offer when you compare them to cash in the bank.’
One example is the 0.125 per cent gilt issued in June 2020 and maturing in January 2028, less than 18 months away. Its coupon is just 0.125 per cent, but the bond is priced at £94.40. Investors could therefore make a £5.60 tax-free gain when they receive £100 at maturity.
Hughes says: ‘The gross equivalent yield on this gilt is 6.8 per cent for a higher-rate tax payer. This compares very favourably with a fixed-rate cash account.’
There are some even more extreme examples, including a gilt issued in May 2020 and maturing in 2061, 35 years from now. The coupon is a scant 0.5 per cent but the bonds are priced at £21.90 putting the interest rate at almost 3 per cent, with the prospect of a chunky tax-free capital gain of £88.10 when the bond matures. Such long-dated issues are not for everyone but they have clear attractions for investors who like to plan ahead or are thinking of passing investments on to children or grandchildren.
And, of course, there is no need to buy and hold. Adrian Bell, of bond specialists Allia C&C, points out: ‘There used to be lots of trading in the old War Loan bonds, which were undated and had a very low coupon.
‘That gave investors an open opportunity to make substantial untaxable gains in an improving interest rate environment. These 2061 gilts are, in some respects, offering people the same thing.’
Investors need to be careful in today’s gilt market. The risks are different from investing in equities but caution and analysis are still essential. Hargreaves Lansdown’s Hal Cook explains: ‘Yields today are higher than they have been for a long time so, in that context, it’s a good time to be buying gilts. But yields could go higher from here, which would mean the price of gilts falling.’
This can be worrying for investors keen on trading, but for anyone who wants to buy and hold, the most important metrics are the current coupon, the price today and the price the Government will pay when the gilt matures. With very long-dated issues, inflation is a key consideration, too. By 2061, for example, £100 may buy considerably less than it does today, eating into the value of an investment.
The Government does offer index-linked bonds, which pay far lower coupons than more traditional gilts but offer interest and capital repayments adjusted to inflation. Plenty of these are also on offer with maturities stretching out from 2028 to 2073 – almost 50 years from now.
For those investors with shorter-term horizons, there are plenty of gilts maturing in one, three or five years’ time, each with different coupons and prices, depending largely on when they were issued.

Investor Ryan Hughes says: ‘Short-dated gilts for higher-rate taxpayers look pretty appealing, and there are some really high rates on offer when you compare them to cash in the bank’
But these are not the only securities available from the Government. The Exchequer also issues Treasury bills, principally maturing in one, three and six months. Intended to cover the Government’s short-term needs, these bills carry no coupon but they are issued at a discount.
A recent six-month bill, for instance, was issued at just over £98 but will pay £100 when it matures in March, implying a yield of just over 4 per cent.
A three-month bill, maturing in December, was issued at £99 and will be repaid at £100, offering an underlying yield of almost 3.9 per cent. These bills are subject to normal taxation unless they are held in an Isa or Sipp – a self-invested personal pension – but they are increasingly popular with investors who are in search of quick returns.
In many respects, government debt offers something for everyone. Income seekers can look for issues with fat coupons. Those looking for capital gains can opt for deeply discounted deals paying negligible interest. And Treasury bills offer swift gains in a relatively straightforward format.
Whatever investors choose, they can also bask in the knowledge the Government has never reneged on its domestic obligations since the Bank of England was established in 1694. The Government is not alone in issuing bonds, however. Companies, charities and non-profit organisations also raise money within the bond market in order to fund their activities.
The principals behind these bonds are the same as gilts – the issue price tends to be £100, coupons are paid twice a year and the borrower is expected to repay its debts when the bonds mature. But there are certain key differences.
Corporate bonds are subject to normal tax rules and, whereas the Government has repaid UK creditors consistently over hundreds of years, companies can default on their debts. If they do, bond holders lose out. To compensate for this risk, companies and charities pay higher coupons, which makes some bonds very attractive to investors prepared to do a bit of homework.
Many household names tap the bond market, from Tesco to Vodafone to the London Stock Exchange itself. And, just like the gilt market, these bonds are traded so prices vary on a daily basis.
Tesco has a bond in the market issued in 1999, maturing in three years and paying 6 per cent interest. Initially priced at £100, the price has moved up and down considerably since the bond was launched, from lows of £97 to a high of more than £135. Today, the bond is priced at £103, offering a yield to maturity of 5.23 per cent.
For investors in search of something a little racier, mortgage specialist LendInvest has a bond maturing in 2032 offering an 8 per cent coupon and currently priced at £101, implying a generous yield to maturity of 7.8 per cent.
The company has to offer investors more because it is perceived as a riskier bet than a cash-rich name such as Tesco.

Many household names tap the bond market. Tesco, for example, has a bond is priced at £103, offering a yield to maturity of 5.23 per cent
Charities tap this market too, particularly those with physical assets such as care home operators Belong or Greensleeves.
Belong bonds, issued in June this year and maturing in 2033, pay a 7.5 per cent coupon but the price has raced up to more than £106, reflecting the deal’s popularity among investors who want to do good while earning well.
At the other end of the spectrum, the Charities Aid Foundation issued a ten-year bond in 2021, paying a 3.5 per cent coupon. But the price has since fallen to £87, meaning the yield to maturity is almost 6.5 per cent. The foundation suffered an unsettling data breach over the summer but the chances of it defaulting on its obligations are negligible.
Gilts and bonds offer particular benefits and their difference from equities can be an advantage in itself. Alex Watts, from Interactive Investor, says: ‘A bond allocation can add a degree of stability to a portfolio, as well as a potentially consistent stream of income.’
In today’s febrile environment, with gilt yields at levels not seen for years, bonds can seem particularly enticing. As always though, balancing the risks against the rewards is essential.
Funds
There are plenty of options for investors who prefer to invest in funds rather than bonds.
Low-cost funds that track gilt indices include the Fidelity UK Gilt Index Fund, the Vanguard UK Gilt Index Fund and iShares Core UK Gilts. Actively managed funds include HSBC Gilt & Fixed Interest fund and the Royal London Short Duration Gilts Fund.
These all provide a broader exposure to the market than buying individual gilts but they do not have the same tax advantages and you cannot buy and hold until maturity, so there is more exposure to trading volatility.
The same rule applies to corporate bond funds but these can be helpful for investors who worry about the risks of individual bonds.
Highly rated active funds include the Royal London Corporate Bond Fund, Schroder Sterling Corporate Bond Fund and Quilter Investors Corporate Bond Fund.
For those who prefer a global approach, PIMCO GIS Global Investment Grade Credit Fund focuses on higher-quality bonds.
How to buy gilts
- Although known as gilts, their names all begin with Treasury, followed by the interest rate, the maturity date and the price.
- Investments can vary from a penny to thousands of pounds, and the dealing is simple, very much like shares.
- The interest rate and the maturity are constant, while the price moves on a daily basis. This affects the yield.
- Platforms such as AJ Bell, Hargreaves Lansdown and Interactive Investor offer a wide selection of gilts, with maturities stretching out from next month to 2073.
- Some platforms display the ‘running yield’, calculated on daily price movements.
- Most do not display the yield to maturity – how much the bond will yield over its lifetime. That can usually be accessed by a search online but investors may want to phone their brokers or platforms to make sure they have the right calculations to hand.
SAVE MONEY, MAKE MONEY
Up to £250 cashback
Up to £250 cashback
2.5% cashback when investing at least £200

4.75% cash Isa
4.75% cash Isa
Trading 212: 1.15% fixed 12-month bonus

£3,000 cashback
£3,000 cashback
£100-£3,000 cashback when opening Sipp
Up to £150 cashback
Up to £150 cashback
Open a savings account with at least £5,000
Welcome bonus
Welcome bonus
Get up to £200 when you invest £100
Affiliate links: If you take out a product This is Money may earn a commission. These deals are chosen by our editorial team, as we think they are worth highlighting. This does not affect our editorial independence. Terms and conditions apply on all offers.