
An old Yiddish proverb, popularised by the lust-driven narrator of Philip Roth’s comic novel Portnoy’s Complaint, says: ‘When the putz stands up, sechel is in the ground.’
‘Sechel’ means common sense. The meaning of ‘putz’ is rather easier to work out.
I thought of that phrase on Sunday evening after reading reports that Jensen Huang, chief executive of AI chipmaker Nvidia, had allegedly been involved with a suspected Chinese spy who, remarkably, shared his surname.
Huang had spent decades building the business he founded in 1993 at the age of 30, transforming it from a fledgling start-up into, at one point, the world’s most valuable company.
Nvidia’s highly advanced semiconductors now power much of the technology industry, with major customers including Microsoft, OpenAI, Meta, Amazon and Tesla.
Tawdry
If you believe the controversy matters only to Huang, Nvidia investors — some of whom are suing over their losses — and possibly a handful of anxious Pentagon officials, think again.
The damaging allegations have helped send Nvidia shares into a tailspin. More worrying still, they could become the trigger for a wider chain reaction that spreads through global financial markets and damages the prospects of millions.
When Nvidia reached its record share price on October 6, the company was valued at $5.7 trillion (yes, trillion). That figure has since dropped to $4.2 trillion, while the stock has fallen by about 16 per cent in just five days.
As reports of Huang’s alleged affair emerged, Nvidia’s market value fell by £200 billion within hours. That may sound modest beside the figures above, but £200 billion is roughly equivalent to the entire value of Shell, Britain’s biggest oil company.

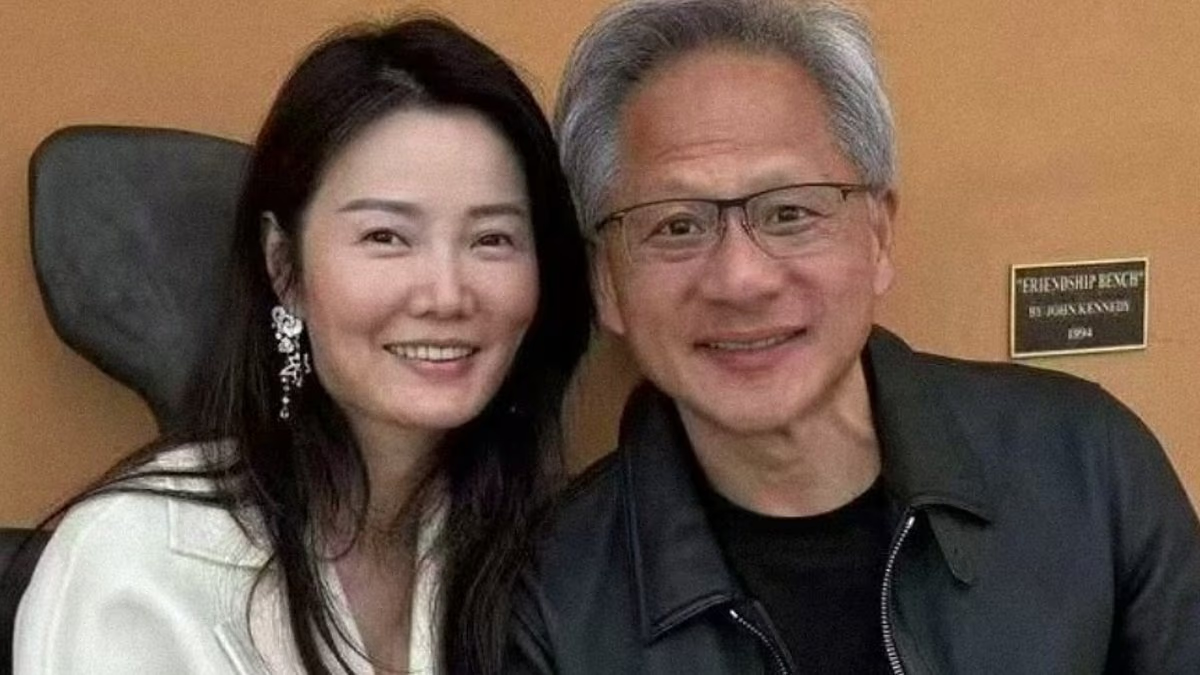
Nvidia chief executive Jensen Huang with Alice Huang. The company’s shares plunged by £200 billion after reports emerged about the business leader’s alleged relationship with a suspected Chinese spy.
Investors around the world are now beginning to wonder whether the scandal could help burst the enormous AI bubble that has driven global markets higher for years.
The International Monetary Fund and other financial watchdogs have repeatedly warned that valuations across the so-called ‘Magnificent Seven’ — Alphabet, Amazon, Apple, Tesla, Meta, Microsoft and Nvidia — have become detached from reality. AI companies including Anthropic and OpenAI have added to the excitement.
The decline in these high-flying stocks has begun, and there may be a long way still to fall.
The Nasdaq, home to many of America’s biggest technology companies, has almost tripled in three years. That surge has prompted a growing number of analysts to argue that the paper wealth assigned to its companies bears little relation to their underlying value.
Elevated share prices also make it easier for companies to raise large amounts of unsecured debt. The Magnificent Seven have accumulated around $3 trillion, a sum equal to roughly 10 per cent of US gross domestic product and not far below the size of Britain’s entire economy.
This vast mountain of borrowing will eventually have to be repaid. It is also substantially larger than the debt concerns that unsettled markets in 2008, when the collapse of confidence in America’s sub-prime mortgage sector brought down the venerable investment bank Lehman Brothers.
The resulting crisis led to a $700 billion rescue of Wall Street and a similarly sized intervention to support Britain’s banks under Gordon ‘We Saved the World’ Brown — a revealing Freudian slip made during Prime Minister’s Questions in December 2008.
Whether Britain was saved or not, the country endured a severe economic downturn after those unprecedented bail-outs of banks deemed ‘too big to fail’. Their executives had overlooked the basic capitalist principle of moral hazard, persuading politicians to make taxpayers responsible for risks taken by the banks themselves.
As with the sub-prime mortgage crisis, I fear the Nvidia controversy could prove to be the kind of ‘black swan’ event capable of setting off a much broader market collapse.
The expression dates back to European explorers in Australia, who had encountered only white swans before discovering their darker-feathered counterparts. Today, it describes an apparently unforeseeable event with potentially devastating consequences.
Markets have already suffered a sharp correction from their peak little more than a month ago.
The steep declines have unsettled investors, many of whom now fear that the AI stocks they have backed for years may deliver disappointing returns for a prolonged period.
Painful

Nvidia semiconductors are used by technology companies including Tesla, Microsoft and OpenAI. Tesla chief executive Elon Musk and Jensen Huang attended the launch of America.gov in September.
Even before America’s midterm elections last week, the Nasdaq had fallen 14 per cent from its record high. Losses have been even greater among smaller US technology companies: online broker Robinhood is down 37 per cent this year, while Silicon Motor Tech has fallen 29 per cent and Marvell Technology 39 per cent.
Two concerns have combined to alarm investors. The first is that increasingly powerful AI systems, if exploited by criminals or hostile states, could threaten the stability of global banking and payment networks. The recent North Korean attack on cryptocurrency exchange Binance, in which $6 billion was reportedly stolen within minutes, has been viewed by some as a warning of what may lie ahead.
The second fear is that falling share prices could bring the multi-trillion-dollar expansion of US data centres to a halt. These vast facilities — in some cases larger than medium-sized towns — house the energy-hungry processors needed to run AI systems.
Many leading AI companies have also extended substantial loans to one another. That prompted Jennifer Harris, an economic scholar and former Biden administration official, to warn last month: ‘The AI boom looks a lot like the housing bubble.’
Fear
Quite so. Anyone with money invested through a pension or a stocks-and-shares Isa should take note.
Many ordinary savers will now be checking their Hargreaves Lansdown or AJ Bell accounts with growing anxiety.
For years, aside from occasional setbacks, investors have become accustomed to the idea that equities will keep rising — particularly when their money is held in a passive index or tracker fund designed to follow the wider market.
The former Chancellor Rachel Reeves appeared so confident that this boom would continue that she sought to encourage British pension funds to invest as much as 10 per cent of their assets in untested areas including data centres, AI and selected private-equity funds. Those investments are now exposed to the growing debt risks surrounding Big Tech.
It is another reason to be thankful that Reeves is no longer at the Treasury.
The music has finally stopped. As the influential American economist JK Galbraith observed, when ‘the bezzle’ — the illusion of wealth created by an unsustainable market boom — begins to unwind, it can destroy economies, jobs and livelihoods.
I fear we may have reached one of those moments.


