
Diversifying your investments has one clear advantage: spreading money across a broad range of assets can materially reduce the risk of suffering heavy losses.
The aim is to ensure that no single investment is large enough to seriously damage your overall returns if it underperforms.
A balanced portfolio can also help smooth out volatility. When one asset falls, another may rise or hold steady, helping to cushion the impact.
However, diversification involves more than dividing your money between shares, corporate and government bonds, property, commodities such as gold and other asset classes.
Investors should also consider geographical spread and exposure to different types of markets, including developed economies, emerging markets and those that fall between the two.
Multi-asset funds and global tracker funds can handle much of this work automatically. But global trackers may leave investors unintentionally overexposed to the US market, particularly its dominant technology companies.

Investment strategy: A balanced portfolio can help reduce volatility by spreading money across different assets
Those who move into specialist or actively managed funds should also examine their own investment biases. It is easy to favour one style, such as value, growth or quality, without realising it, even though each tends to lead the market at different points in the cycle.
The account or wrapper used to hold investments matters too. Each option has its own tax benefits, restrictions and disadvantages, while government rules can change over time—although usually not all at once.
Workplace pensions, for instance, are generally low-cost investment products supported heavily by employers and the government. For many people, the default fund selected through automatic enrolment is the simplest and most straightforward way to begin investing.
The trade-off is limited access: pension savings are locked away until age 55, rising to 57 from spring 2028. Any withdrawals beyond the 25 per cent tax-free lump sum are taxed as income.
With that in mind—and after first building an emergency cash reserve in a cash Isa—opening a stocks and shares Isa can be a practical, tax-efficient next step.
Although contributions are made from money that has already been taxed, investments held in the Isa remain free from tax and can be accessed at any age.
Diversifying your investments: Getting started
“Spreading your money across different investments can make the journey less bumpy because assets do not all perform in the same way or move in tandem,” says Rob Morgan, chief analyst at Charles Stanley Direct.
“No single area of the market stays on top indefinitely, which is why holding a mixture is important. A portfolio containing too few investments, or investments that are too similar, may perform well for a time but can also deteriorate quickly.”
Even so, diversification has a practical limit. Spreading money too thinly can be just as unhelpful as holding too narrow a selection.
James Scott-Hopkins, founder of wealth manager EXE Capital Management, says: “There is diversification and there is over-diversification.”
“Diversification is essential for reducing volatility, but taking it too far is likely to result in weaker returns. Like a good diet, the answer is moderation.”
“If you spread yourself too widely, you simply end up reverting to the market average, in which case you might as well buy a tracker fund. At the same time, there is a concentration risk problem: almost half of the S&P 500 is invested in businesses linked to artificial intelligence.”
Darius McDermott, managing director at FundCalibre, also warns that diversification may offer limited protection during an extreme market sell-off.
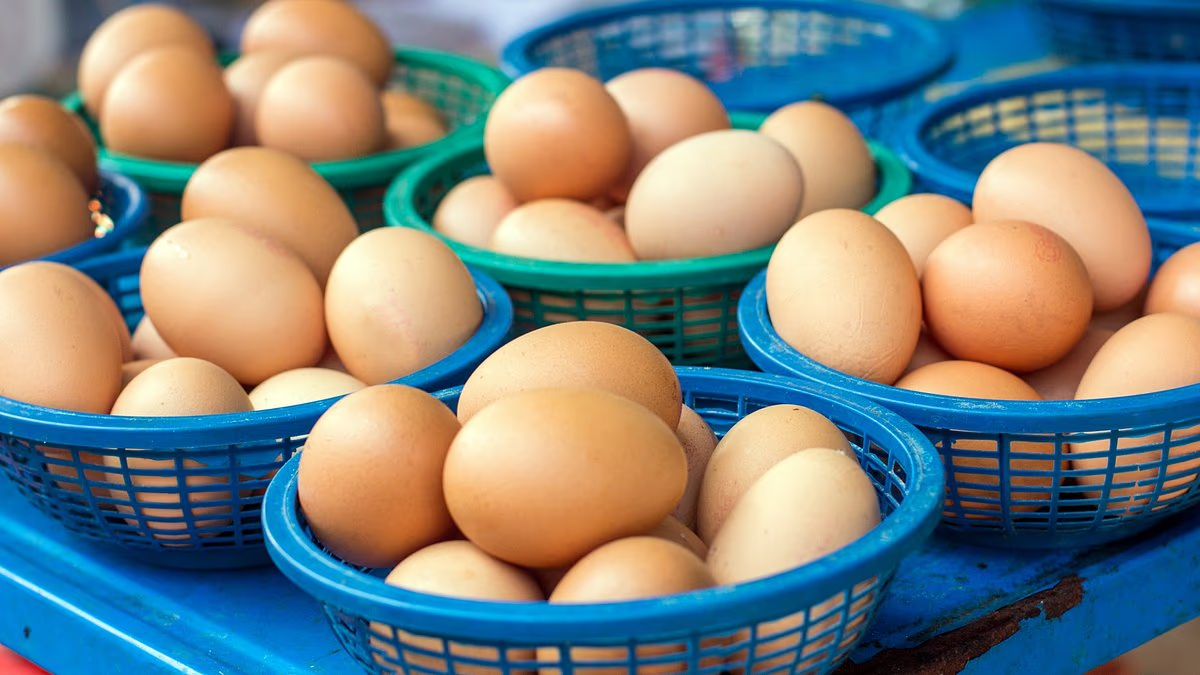
‘Diversification is often described as not putting all your eggs in one basket,’ he says.
‘But that’s only half the story – if every basket sits on the same cart, it doesn’t matter how many you have; one pothole and they all bounce the same way.’
Are your current investments diversified enough?
You need to consider this in relation to your investment goals, time you plan to spend investing and a few other factors – there are no absolute rules.
Morgan says you should also think about how much volatility you are prepared to accept, and take into account that this can change over time.
He explains that taking on too little risk in your 20s and 30s could be a wasted opportunity.
But if you let your investments get too concentrated later in life, when you are looking to cash in or start drawing an income, you could become a victim of volatility at just the wrong moment.
‘The longer the time horizon for the intended investment the more an investor could consider allocating to shares.
‘For instance, when investing for retirement multiple decades away investing in shares exclusively, or almost exclusively, could be considered.’
So how do you check whether you have spread your risk sufficiently well? Morgan says these are the warning signs that you need to carry out a review.
– Your portfolio value is very volatile – it experiences big ups and downs.
– You only hold a small number of shares or specialist funds, or you hold few broad investments such as trackers and multi asset funds.
– Most of the investments you own appear to move in tandem – they all go up and down at the same time to a greater or lesser extent.

James Scott-Hopkins: Diversification is key to reducing volatility but overdoing it will likely mean poorer returns
How to make your investments more diversified
You need to think about this on two levels, namely asset classes like shares and bonds, and then numbers of holdings within each area, says Morgan.
‘A “balanced” approach might be to consider 60-80 per cent exposure to shares and 20-40 per cent to bonds and other assets that could have the effect of dampening down the typically greater ups and downs of the stock market.’
He says if you hold individual shares there needs to be more diversification than with funds – 30 to 40 holdings wouldn’t be considered too many, but you need to commit to monitoring them.
Meanwhile, he thinks 10-20 funds is an appropriately broad portfolio, because a less than 5 per cent position isn’t going to have a meaningful effect on your returns unless it does exceptionally well or badly.
And holding just one multi-asset fund is a useful shortcut – more on this below.
‘It’s important to strike a balance. A portfolio shouldn’t become a “stamp collection,” an unstructured array of holdings,’ says Morgan.
‘It’s best to start with overall objectives and strategy and then populate certain areas with just one or two funds in each area rather than an unstructured clutter.’
James Scott-Hopkins of EXE Capital Management reckons the key is to compile funds or investment trusts from a few conviction managers who focus on different companies around the world.
He suggests:
– A foot in the AI door to benefit from momentum investing;
– Another in companies that are hard for competitors to muscle in on;
– And, importantly, another in companies that have strong cash flow and pricing power to counter inflation.
Scott-Hopkins tips the Polar Capital Global Insurance fund, run by the same manager for 25 years and averaging 10 per cent growth a year.
‘Everyone needs insurance, even when markets move into bear market territory. It is a fund that is perfectly negatively correlated to equities.’
He also likes the almost 100-year-old Brunner Investment Trust, which is free to select the world’s best companies regardless of where they are listed.
‘It’s where they generate their revenues that counts. The portfolio of around 50 stocks offers broad diversification at a time of increased concentration at the index level.’

Darius McDermott: If every basket of eggs sits on the same cart, one pothole and they all bounce the same way
Diversification strategies to consider
Darius McDermott of FundCalibre offers the following fund ideas.
Bonds: Strategic bond funds such as GAM Star Credit Opportunities or Invesco Tactical Bond give you flexible access across the fixed income spectrum.
Absolute return: BlackRock European Absolute Alpha aims to deliver positive returns whatever markets do, using long and short positions so you’re not solely reliant on prices rising.
Real assets: Cohen & Steers Diversified Real Assets or First Sentier Global Listed Infrastructure offer ballast from toll roads, utilities and infrastructure, rather than corporate profits alone.
Growth, value and quality: Styles take it in turns to lead. Value funds like Ranmore Global Equity buy cheap shares well below the market average, with a tempting income on top.
Quality growth funds like IFSL Evenlode Global Equity back reliable names such as Mastercard and Visa for the long haul.
Both have very different flight paths from each other – and the index – and owning both smooths returns rather than tracking the market.
Multi-asset: Jupiter Merlin Balanced Portfolio holds 40-85 per cent in equities alongside bonds and other assets in one diversified package.
How to diversify with a multi-asset fund
Multi-asset funds are ready-made investments aiming to provide everything you need in one package, according to Morgan.
‘If you have a good idea of the risk you want to take, and you want a hands-off approach to managing your investments, they could be a great option.’
‘These funds are useful for investors who want to leave most of the investment decisions and rebalancing to experts but personalise their portfolio through their own selection of funds and shares at the edges.’
But he warns that no multi-asset fund offers a perfect solution for everyone, and they can come with different risk levels, so either choose the one most appropriate for your needs or consider buying a combination.
Dangers of diversifying with only ONE global tracker fund
Buying a global tracker fund is still a popular way to get broad all-in-one exposure to the whole world’s stock markets – but these days it comes with a warning attached.
These funds simply clone market performance and are passively run – there is no active management – and are cheap as a result.
However, they involve a concentrated bet on US markets, which make up around two-thirds of global markets, and therefore the tech and AI behemoths that dominate Wall Street.
If you only hold one global tracker fund and nothing else, you need to be aware of this over-exposure, and consider whether you want to mitigate the risks – various methods of doing so are explained below.
Morgan says a global tracker fund can be a good first option for those not able to spend time researching investments, and a building block around which other investments can be arranged.
‘Funds or ETFs such as Fidelity Index World or iShares Core MSCI World UCITS ETF provide straightforward access to many share markets around the world and therefore thousands of different companies.
‘However, be aware that traditional US and global passive funds are heavily skewed towards large US stocks.
‘Since these companies are often interlinked in terms of their fortunes, and valuations already reflect high expectations, incorporating a broader range of elements should ensure a portfolio isn’t flying on the single engine of big tech.’

Jason Hollands: So-called Magnificent Seven – Nvidia, Microsoft, Apple, Alphabet, Amazon, Meta and Tesla – represent a third of the S&P 500 Index
Jason Hollands, managing director of Bestinvest, says: ‘The traditional assumption that investing in an index tracker automatically delivers broad diversification deserves renewed scrutiny.’
He points out that the so-called Magnificent Seven – Nvidia, Microsoft, Apple, Alphabet, Amazon, Meta and Tesla – represent a third of the S&P 500 Index.
And Hollands says that if you add in semiconductor firms Broadcom and Micron Technology, both benefiting from vast spending on AI infrastructure, the top ten stocks in the S&P 500 now represent 37.4 per cent of the entire index.
He adds that it’s not just a US issue because the AI investment boom is increasingly reshaping regional indices around the world.
The MSCI Emerging Markets Index currently has close to 30 per cent exposure to three semiconductor companies – Taiwan Semiconductor Manufacturing Company (TSMC), Samsung Electronics and SK Hynix.
Hollands explains that the dominance of these companies is currently so pronounced that Taiwan and South Korea are now the two largest country positions within the MSCI Emerging Markets Index, with China and India pushed into third and fourth places respectively.
‘As recently as 2020, China accounted for around 43 per cent per cent of the MSCI Emerging Market Index – it is now 18.9 per cent.
‘Many investors buying an emerging markets tracker may assume they are gaining broad exposure to the growth prospects of a swathe of developing economies.
‘Increasingly, however, they are inadvertently making a significant bet on a small number of semiconductor manufacturers and, by extension, the continuation of the global AI investment cycle.’

Rob Morgan: Taking on too little risk in your 20s and 30s could be a wasted opportunity
How to avoid the global tracker trap
Alternatives to traditional global trackers and funds you could buy in tandem to them are explored below.
Equal weighted funds
These allocate an equal weight to each individual company in an index like the US S&P 500, rather than the usual method of weighting them according to market value.
‘This reduces dependence on a handful of dominant stocks and can provide broader participation across the market,’ says Hollands.
‘One strategy for those worried about concentration risk might be to shift part of an existing position in a conventional market-cap weighted tracker into an equal weighted version.’
He suggests for US exposure you could hold both a S&P 500 Index tracker and the Legal & General S&P 500 Equal Weight Index fund.
And in addition to a global tracker, you could buy the Invesco MSCI World Equal Weight UCITS Exchange Traded Fund.
Morgan says if you are unsure about being overly invested in ‘big tech’ then an equal weight strategy will place more emphasis on areas such as industrials, real estate, materials and utilities
‘Broadly, the approach tilts towards cheaper “value” stocks and away from more expensive “growth” stocks.
‘Xtrackers S&P 500 Equal Weight UCITS ETF tracks the same number of holdings as a standard S&P 500 ETF but weights the components equally – at approximately 0.2 percent presently – rather than by size based on relative market capitalisations.
‘Holdings are rebalanced to equal weighting on a quarterly basis.’
Defensive global equity funds
Morgan says as an alternative or complement to a global tracker, you could buy a defensively minded global equity fund, or a global equity income fund targeting resilient, dividend-paying stocks
‘For instance, JO Hambro Global Opportunities offers a blend of offense and defence with the managers focused on quality and value.
‘Zero exposure to Nvidia, Apple, Amazon, Meta, Broadcom and TSMC make the fund a more defensively minded diversifier to a global tracker.
‘Meanwhile, Trojan Global Income focuses on quality and resilience as a priority with a preference for more predictable businesses that can quietly compound their earnings over time.

Factor funds
These are ‘next generation’ passive investments, maintaining broad diversification but still without relying on the judgment of a fund manager, according to Hollands.
They hold a wide basket of shares but are weighted according to fundamental characteristics, rather than simply market capitalisation, he explains.
Hollands suggests the Invesco RAFI US Fundamental Value ETF, which owns the 1,000 largest US companies,
‘Instead of weighting each holding on market-cap, it does so on four criteria: sales (averaged over the prior five years), cash flow (averaged over the prior five years), book value (at the review date), and dividends (total dividend distributions averaged over the last five years).’
DIY INVESTING PLATFORMS
AJ Bell
AJ Bell
Easy investing and ready-made portfolios
Hargreaves Lansdown
Hargreaves Lansdown
Free fund dealing and investment ideas
interactive investor
interactive investor
Flat-fee investing from £4.99 per month
Freetrade
Freetrade
Investing Isa now free on basic plan

Trading 212
Trading 212
Free share dealing and no account fee
Affiliate links: If you take out a product This is Money may earn a commission. These deals are chosen by our editorial team, as we think they are worth highlighting. This does not affect our editorial independence.
Compare the best investing account for you


