
When every pound in your savings has been earned through hard work, watching hundreds or even thousands of pounds vanish within days is deeply unsettling.
It is even harder to accept when the trigger is something entirely beyond your control.
Millions of British savers have seen the value of their pensions and Isas fall this week after reports emerged that a middle-aged man thousands of miles away had an affair.
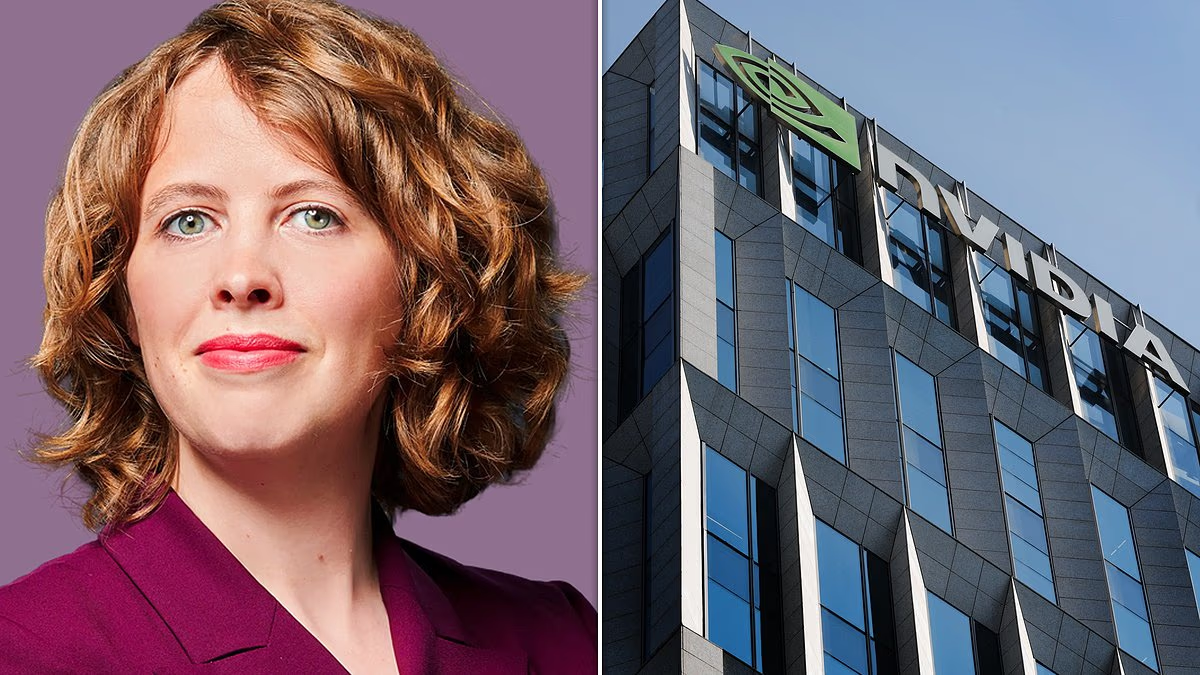
On Monday, Nvidia shares plunged, wiping as much as £300 billion from the company’s value at one point, after the chipmaker began investigating its boss, Jensen Huang, over an alleged affair with a suspected Chinese spy.
If you have never bought Nvidia shares directly, you may wonder why the company’s share price — or its chief executive’s personal life — should affect you.
The answer is that Nvidia has become such a giant that many of us own a stake in it indirectly.

As the world’s second-largest company, Nvidia represents about 5 per cent of the value of developed global stock markets

Nvidia has launched an investigation into chief executive Jensen Huang over an alleged affair with a suspected Chinese spy
As the world’s second-largest company, Nvidia alone accounts for roughly 5 per cent of the value of developed global stock markets.
Anyone invested in a global, US or technology fund — or simply paying into a workplace pension — is likely to have some exposure to Nvidia.
I checked the value of my own investments this morning. It was not a pleasant experience, and I immediately wished I had waited.
The fall in Nvidia’s share price is only the latest blow. Technology stocks had already been battered in recent days after the market’s rollercoaster response to last week’s US midterm election results.
Against that unsettled backdrop, the Government’s proposals last week to remove much of the responsibility for investing our retirement savings from individuals may look surprisingly attractive.
The plan would allow savers to pool their retirement funds with others, have them invested on their behalf and receive a regular income, rather than managing their pension pots alone.
Announcing the so-called ‘guided retirement’ proposals, pensions minister Torsten Bell said savers could choose a stable income for life ‘without having to become investment experts overnight’.
Under such an arrangement, we would no longer need to worry so much about market volatility, estimate how long our money might need to last or fear running out of cash.

Rachel argues that financial education, saving and investing should be taught from an early age
A collapse in Nvidia shares? That would be someone else’s concern. A global stock market rout? Again, the risk would be passed to another party.
For some savers, the proposals could provide a straightforward answer — although anyone seeking a guaranteed income for life can already access one through an annuity.
But there is a significant trade-off. Those who join the new scheme would surrender much of the flexibility and control they currently have over their retirement savings.
They might not be able to withdraw a larger sum when circumstances demand it, or reduce their income in a year when they need less. Changing course would also be difficult.
Worse still, the policy risks reinforcing the outdated and misleading idea that investing is too complicated for ordinary people and should be left to professionals.
A decade ago, pension freedoms gave us the power to decide how to use our retirement pots. It would be deeply disempowering to hand that control back.
It would also represent a failure if savers do not feel supported and confident enough to use the freedoms they have been given.
Rather than removing people’s agency by default, it would be far more empowering to help everyone develop the confidence to make informed financial decisions.
Financial education should begin in schools, with conversations about money, saving and investing continuing throughout our lives.
I have started spotting the Government and industry-backed campaign to improve investment knowledge — fronted by a red squirrel in a hoodie — on billboards and taxis. I wish the campaign well, but changing attitudes will require more than that.
With the right knowledge and confidence, even turbulent financial markets do not have to be intimidating.
If retirement is still some years away, falls in Nvidia and other technology stocks can be viewed in perspective. Over the long term, they may amount to little more than a temporary setback — and investors will have the opportunity to buy at lower prices.
For older savers, confidence can make it easier to stay the course and trust the portfolios they have built.
Pension freedoms will fail if retirees are expected to become ‘investment experts overnight’, as Torsten Bell put it. That is an appalling expectation. They can succeed, however, if people are helped to build their knowledge over a lifetime.
Rachel.rickard@dailymail.co.uk
SAVE MONEY, MAKE MONEY
Up to £300 cashback
Up to £300 cashback
Receive £25-£300 cashback when depositing at least £300

4.75% cash Isa
4.75% cash Isa
Trading 212: includes a 0.90% fixed 12-month bonus
£2,500 cashback
£2,500 cashback
Get £250-£2,500 cashback when opening a Sipp
Up to £150 cashback
Up to £150 cashback
Open a savings account with a deposit of at least £5,000
Welcome bonus
Welcome bonus
Receive up to £200 when you invest £100
Affiliate links: This is Money may earn a commission if you take out a product. Our editorial team selected these deals because we believe they are worth highlighting. This does not affect our editorial independence. Terms and conditions apply to all offers.


