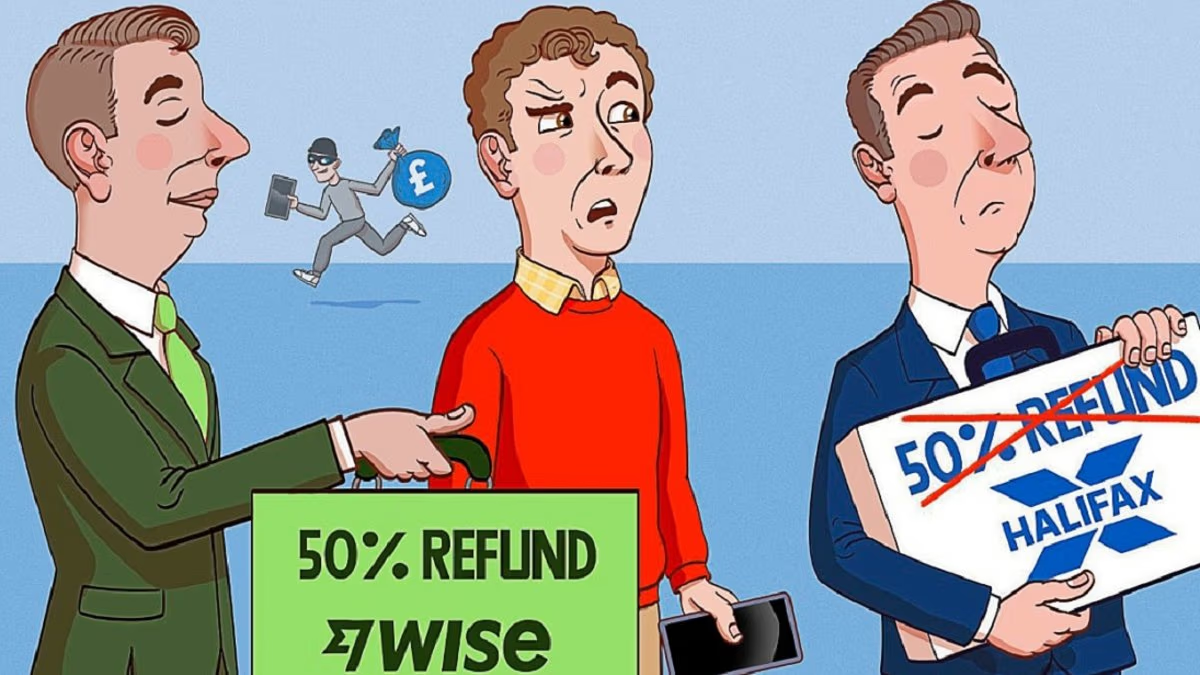

On September 2, a fraudster accessed my Giffgaff mobile account and completed a SIM swap at 4.47am, despite not having my phone.
Someone accessed my Giffgaff mobile account and carried out a SIM swap at 4.47am without having my physical device.
The criminal took control of the account and went on to access several of my bank accounts. Loans were applied for in my name with Halifax, while other lenders also received loan quote requests.
Around £1,900 was moved from my Halifax account to my Wise currency account, followed by several payments.
Even after I alerted Wise, two further transactions were made. Halifax refused to cover my losses because the money had been sent to my genuine Wise account.
Wise treated the matter as a ‘shared responsibility’ case and refunded half of the money, arguing Halifax should pay the remainder. Halifax has refused. Can you help?
C.W., Essex.

Halifax initially refused to refund the rest of a reader’s losses after SIM-swap scammers transferred money to another genuine bank account
A SIM swap scam is a form of identity theft in which criminals persuade a mobile network to transfer a victim’s phone number to a SIM card under their control.
Once scammers control a phone number — often after breaking into the victim’s email account — they can access banking services, reset passwords and approve payments using security codes sent to the phone, frequently without the victim realising.
It is impossible to know exactly how the fraudsters obtained your personal information, but it was enough to take control of your Halifax account.
Whatever the route, they used your details to hijack your email address and mobile number, locking you out of your devices.
Because the payments were plainly unauthorised, you should normally receive an automatic refund under the Payment Services Regulations 2017.
Under these rules, banks generally have to reimburse victims by the next working day after a fraud is reported. A refund can only be refused if the bank proves the customer acted fraudulently or was grossly negligent. Where more than one financial firm is involved, liability may be divided — which explains why Wise initially offered to refund only half.
Loans taken out fraudulently in someone else’s name should also normally be cancelled, with any repayments returned.
Thankfully, Halifax cancelled the £3,000 fraudulent loan and repaid the associated instalments. However, it continued to reject responsibility for the money that passed through your Wise account.
When I asked Halifax to review the case, it confirmed information you already knew about the £3,000 loan and an Uber Eats payment you had not made.
The bank accepted that both were unauthorised, confirming the loan had been cancelled and the Uber Eats payment refunded.
Regarding the three transfers to Wise, worth £1,866 in total, and the four card payments that followed, Halifax acknowledged that you had previously been told to resolve the issue with Wise. It has now changed its position.
After my intervention, Halifax accepted that the disputed payments were part of the wider account takeover and agreed to refund £922 — the outstanding amount not already repaid by Wise.
A Halifax spokesman says: ‘We’re sorry our customer was the victim of fraud and for the delay in resolving things. We’ve looked again and will be refunding him for the rest of the money he lost.’
You were pleased with the outcome, although Wise had previously offered just £110 to acknowledge its failings. After I became involved, it paid an additional £140 because it had also wrongly closed your account during its investigation. Since the fraud began with your Giffgaff account, I also asked whether the mobile provider had done enough to safeguard you.
Giffgaff said it had taken all reasonable steps and declined to pay compensation, arguing that the fraudsters had obtained the relevant information from another source.
A spokesman says: ‘To ensure account security, we recommend members use strong, unique passwords for each account and account recovery, as an additional layer of security.’
Warning signs of a SIM swap include an unexpected loss of mobile service or a message confirming a SIM replacement you did not request. Contact your network provider and banks immediately, then change your passwords.
You may also want to switch off text-message alerts so criminals cannot intercept one-time authorisation codes.
To reduce the risk of SIM-swap fraud, ask your mobile network whether you can add a dedicated PIN or password that must be provided before a replacement SIM or eSIM is activated.
Month-long Isa transfer delay leaves saver chasing lost interest
I opened a one-year fixed-rate cash Isa with Yorkshire Building Society (YBS) and arranged for £143,934 to be transferred from my Isa with Trading212.
FIND OUT MORE: Harry Shum Jr Ethnicity, Parents, Wiki, Biography, Age, Wife, Children, Net Worth & More
YBS said the transfer had completed a few days later. But after hearing nothing further, I contacted the building society a week afterwards and discovered it had supplied Trading212 with the wrong account details, meaning the money had been returned.
Trading212 said it made a second attempt, but almost a month went by without YBS confirming whether my money had reached the new Isa. I have lost interest on the balance during this delay.
K.W., Mirfield, West Yorkshire.
An Isa transfer should be a routine process. You completed the necessary paperwork with YBS, which then became responsible for arranging the move.
Although the transfer request came from YBS and the form was completed correctly, the building society sent the funds back to Trading212 once. After a second attempt, the transfer then appeared to stall.
I asked YBS to investigate, but it took several days before the building society responded.
YBS eventually admitted that incorrect account information had apparently been sent to Trading212 twice.
The building society said it would correct the error immediately and backdate the Isa to the original transfer date, ensuring you did not lose interest.
A YBS spokesman said: ‘If issues arise during a transfer or application process, we work to identify the cause, put matters right as quickly as possible and ensure customers are not disadvantaged.
‘We apologise for the inconvenience customers may experience when delays occur.’
- Write to Sally Hamilton at Sally Sorts It, Money Mail, Northcliffe House, 2 Derry Street, London W8 5TT or email sally@dailymail.co.uk. Include your phone number and address, together with a note addressed to the organisation involved giving it permission to speak to Sally Hamilton. Please do not send original documents, as we cannot accept responsibility for them. Our News Outlet cannot accept legal responsibility for the answers provided.
SAVE MONEY, MAKE MONEY
Up to £300 cashback
Up to £300 cashback
£25-£300 cashback on at least £300

4.75% cash Isa
4.75% cash Isa
Trading 212: 0.90% fixed 12-month bonus
£2,500 cashback
£2,500 cashback
£250-£2,500 cashback when opening Sipp
Up to £150 cashback
Up to £150 cashback
Open a savings account with at least £5,000
Welcome bonus
Welcome bonus
Get up to £200 when you invest £100
Affiliate links: If you take out a product This is Money may earn a commission. These deals are chosen by our editorial team, as we think they are worth highlighting. This does not affect our editorial independence. Terms and conditions apply on all offers.


