Pressure was building within Labour today for wealth taxes to feature in the Budget, despite warnings that targeting high earners and investors could ultimately reduce revenues.
Dale Vince, the millionaire eco-tycoon and Labour donor, has called for an increase in capital gains tax (CGT).
He argued that combining a CGT rise with the removal of interest payments to commercial banks on their deposits at the Bank of England could help finance a higher personal allowance for millions of people.
However, Chancellor John Healey has been warned that another tax raid on wealth creators could prove disastrous, suppressing revenues further amid concerns that wealthy people are already leaving the UK.
Andy Burnham and Mr Healey are searching urgently for ways to balance the books while meeting costly spending commitments.
The crisis in the Middle East is thought to have consumed much of the Chancellor’s financial “headroom” for meeting his fiscal rules.

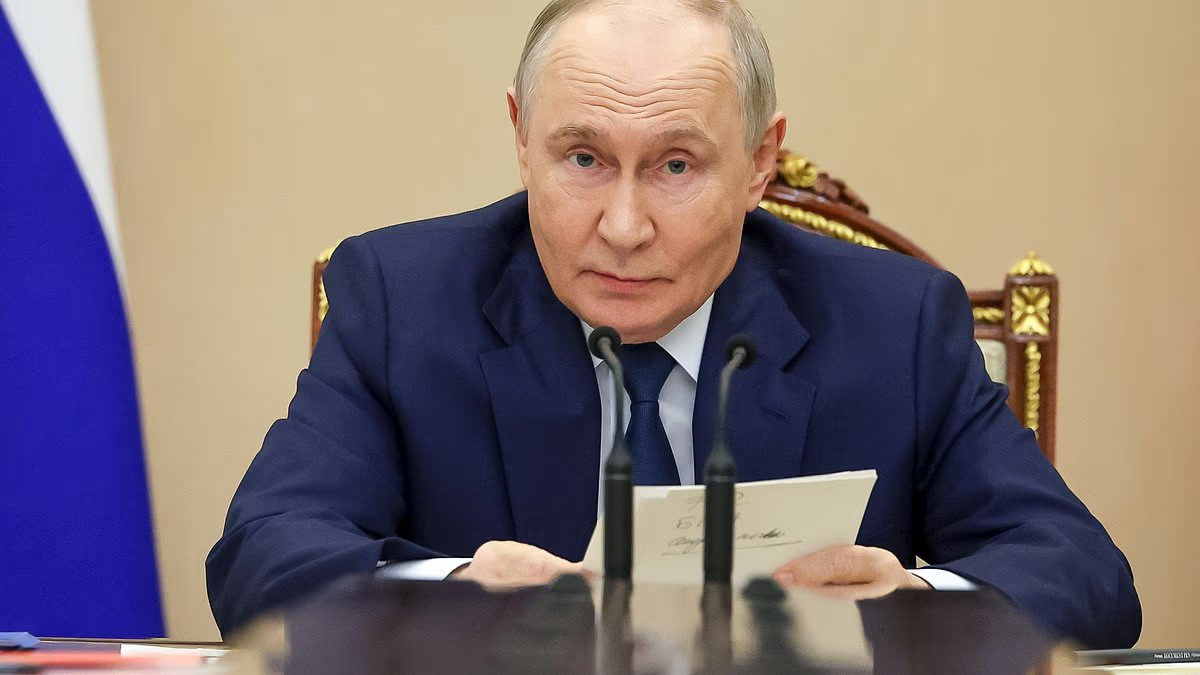
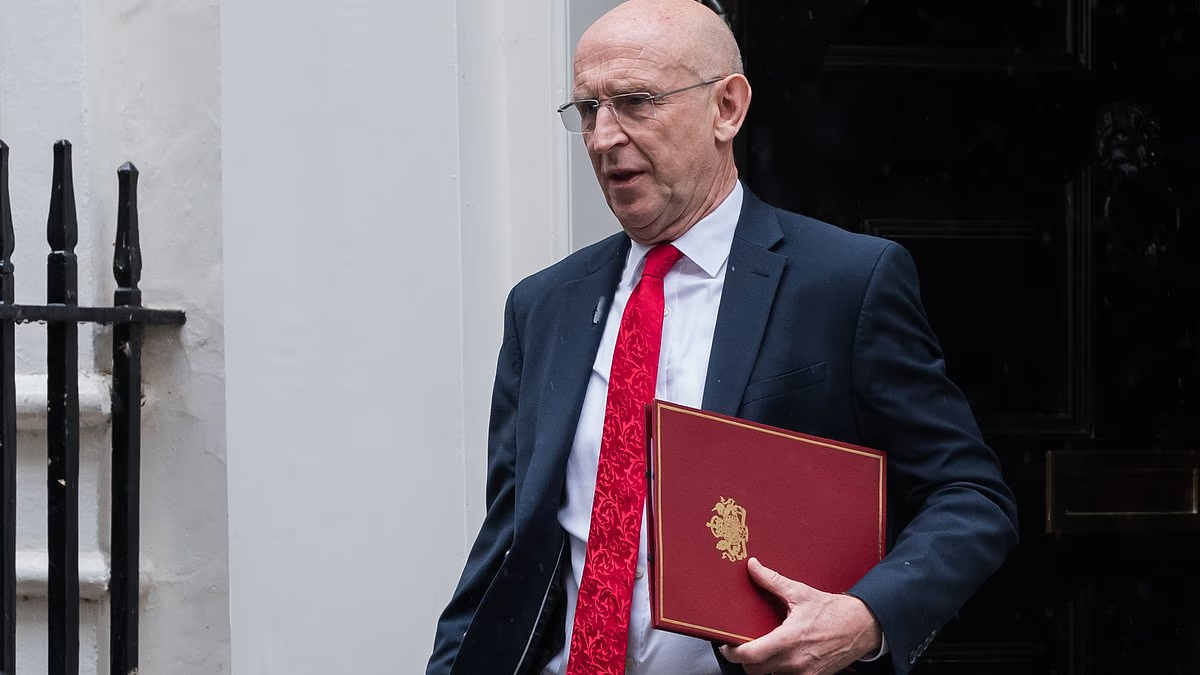
Andy Burnham and John Healey, pictured, are seeking ways to balance the books and finance major spending commitments

Millionaire eco-tycoon and party donor Dale Vince has called for capital gains tax (CGT) to be increased
Mr Burnham, meanwhile, has highlighted his commitment to easing the cost-of-living burden as rising energy bills push up inflation and the Bank of England prepares to increase pressure on mortgage borrowers through higher interest rates.
During last week’s annual TUC conference, unions repeatedly urged ministers to raise more money from banks and wealthy individuals.
In his submission ahead of the October 28 Budget, Mr Vince said matching CGT rates with income tax rates — reaching as high as 45 per cent — could raise £14billion.
He said that, combined with ending interest payments to commercial banks, the proposal could fund an increase in the personal allowance of roughly £3,000, taking it to £15,570 a year.
That figure would be just below the level the allowance might have reached if it had not been frozen in 2021.
Mr Vince described the current system as “backwards” and urged ministers to “put money into the pockets of the people who will spend it” in an effort to revive the economy.
Speaking on BBC Radio 4’s Today programme, he said: “It will cost £20billion actually to restore the income tax freeze, which is really robbing people, particularly hard-working people.
“We pay interest to the banks every year totalling about £30billion, you know the banks that don’t really pay us any money for our deposits with them, we through the Bank of England pay them 4 per cent at the moment for the money that they’re sat on… £30billion, take that back, pay for the income tax allowance, and have £10billion in change.”
The Treasury’s own forecasts, however, suggest that a 10-percentage-point increase in CGT would reduce revenues by £3.5billion by 2028-29.
Kevin Hollinrake, the Conservative Party chairman, described a CGT increase as potentially “the dumbest economic policy of all time”.
“The clue is in the name – Capital Gains Tax – means gains on capital that you’ve invested and put at risk,” he said.
“Tax it as if there’s no risk involved and fewer people will invest. Bad for jobs, bad for the economy.”
Mr Hollinrake insisted it would also be ‘bad for tax receipts’.
‘You only pay CGT when you sell stuff, so people who’ve invested and own stuff already will defer selling stuff until a future govt sees sense and lowers CGT,’ he added. ‘Utterly stupid sixth-form economics.’
Former Conservative Treasury minister David Gauke also cast doubt on whether the policy would work.
Join the discussion
Would YOU support raising the tax-free personal allowance to £15,570?

Mr Burnham has been talking up his commitment to helping Brits with the cost-of-living
Sir David told BBC Radio 4: ‘Anything that sounds too good to be true is almost certainly too good to be true.
‘I’m very sceptical that you can raise that sort of money from the banking sector, without it having a significant impact on competitiveness, a significant impact on lending to small businesses in particular.’
He added: ‘There isn’t, I’m afraid, an easy answer whether that’s the banking sector or a few high net worth individuals, our tax system is already very dependent upon the very wealthy. I’m afraid that answers that sort of sound terrific and mean ordinary people are unaffected are not going to be credible.’