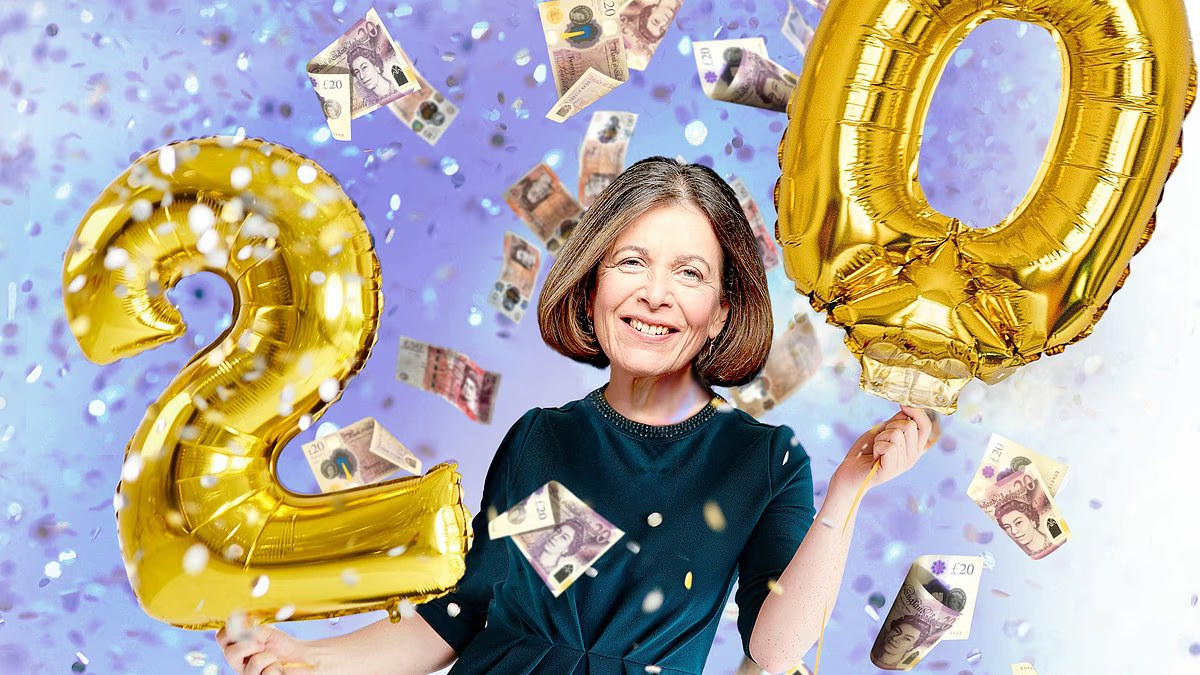

In October 2006, the iPhone had yet to appear, the word ‘woke’ was not part of everyday language and velour tracksuits were considered fashionable. That was the month I wrote my first Midas share tip, highlighting gas specialist BG Group.
Since then, I have made hundreds of recommendations, ranging from tiny tiddlers to global multinational companies.
Below, I have set out 12 lessons for successful share-picking, along with an in-depth look at six companies I would choose today.
From the outset, I have followed a few basic rules. I try to speak to someone at the top of every company I cover, and I only write about businesses I understand — including how they make money and where future growth could come from. Crucially, the price must also be right.
In the hunt for overlooked companies that could make readers richer, I have spoken to thousands of chairmen, chief executives and finance directors. Some were charming, others surly, and most — though not all — were intelligent and highly knowledgeable.
Those conversations generate valuable information and fresh ideas, but they are only part of the process. I also carry out independent research online and in print, while seeking the views of City analysts and other specialists. So far, the approach appears to be working.
There have been some painful mistakes — bruising experiences for which I can only apologise. Even so, my recommendations have succeeded more often than they have failed.
I have consistently outperformed the FTSE 100, with several exceptional winners along the way. A handful have even become ‘ten-baggers’ — shares that have increased tenfold since I first recommended them.

Joanne Hart wrote her first Midas share tip in 2006 and has made hundreds of recommendations since
12 tricks to pick winning shares
So, what have I learned over two thrilling decades?
1. Diversification is essential. Nobody gets every decision right, so spread your risk across a broad selection of stocks.
2. Shares generally deliver their best results over several years. Businesses need time to expand, and companies that grow steadily often produce the strongest returns.
3. Dividends matter. Reinvested income can make a substantial difference to total returns over time.
4. Management teams are important. Capable, honest and transparent leaders can make a significant difference — and the share price often reflects it.
5. Beware the snake-charmers. When an investment opportunity seems too good to be true, it probably is.
6. Valuation is critical. A company may be performing perfectly, but if all that success is already priced into the shares, there may be little reason to buy.
7. Do your homework. Can the company deliver what it promises? Do its financial figures stand up to scrutiny? Is it offering customers something they want at a price they are willing to pay?
8. Never buy shares in a business whose management cannot clearly explain what the company does.
9. Never invest money in the stock market that you cannot afford to lose.
10. Do not be afraid to sell part of a holding after the shares have performed strongly. Nobody loses money by securing a profit.
11. Shareholders are owners in a business. Think about that before you invest your precious cash.
12. Be brave. Adventure can be fun, particularly within a diverse portfolio.
3i Group
Investment specialist 3i Group is a case in point. Tipped in 2012, when the shares were £2.16, they have since soared to £24.16, so an investment of £1,000 back then would be worth about £11,000 today, supplemented by £2,600 of dividends – a tasty total return.
The performance is testament to chief executive Simon Borrows, appointed in 2012 and at the helm to this day.
Founded after the Second World War to fund small businesses, 3i evolved into a private equity pioneer and floated on the stock market in 1994. By 2012, however, it was in a sorry state.
Borrows was parachuted in to help and Midas recommended the stock a few months later, after the former investment banker spent £6million of his money on shares. He slashed costs and reduced its investments from 140 to 30 firms, with an emphasis on long-term stewardship and active investment.
One investment from those days remains in force – Dutch discount retailer Action.
Back then, there were just 250 stores. Now there are 3,500 and Borrows hopes to more than double that number.
Action dominates 3i’s portfolio, but other long-term investments include healthcare products firm Royal Sanders and Rotherham-based seals business AESSEAL. 3i also owns 29 per cent of independently listed 3i Infrastructure, whose investments range from low-carbon energy to sub-sea fibre-optic cables. Years of success took 3i shares to more than £44 last October but a disappointing update from Action sent the stock down to £22 this year.
The price has recovered a little since then and many supporters believe it deserves to go higher.
Borrows has also been acquiring shares over the past year – a good sign.
Long-term investors have done well with 3i but now is not the time to sell. New punters might also like to follow Borrows’ lead.
Traded on: Main market Ticker: III Contact: 3i.com
I’m Simon Lambert, publisher of This Is Money, and you need to know that your pension, savings and property could soon be under attack.

On October 28, Andy Burnham’s government will set out its Budget. We don’t know what they will do, but we do know about tax raids already on the way. The best thing you can do is get prepared. So I’ve called on some of Britain’s leading financial experts to create my new six-week plan. I’ll cut through the noise and take you step-by-step through everything you need to do to protect your money.
Don’t wait. Click here and sign up to Protect Your Money now.
Anglo Asian Mining
Copper and gold producer Anglo Asian Mining would seem to have little in common with 3i.
Based in Azerbaijan, the group is listed on Aim, chaired by 82-year-old Khosrow Zamani and has little truck with UK corporate governance convention.
But, like 3i, it has delivered the goods, soaring from just above 40p when I tipped the stock in 2018 to £4.15 today.
Back then, Anglo Asian was a small-scale gold miner, dominated by one site. Now the group is transitioning into a mid-sized copper, gold and silver group with three mines in production, two expected to come on stream by 2030 and several more under licence.
Copper is a key plank in Anglo Asian’s transformation. Production is set to triple to more than 20,000 tons from last year to this year, and a target of about 50,000 tons per annum is in sight over the next five years. At the same time, gold production is set to remain stable at 20,000 to 30,000 ounces per year, generating plenty of cash for shareholders.
Anglo Asian had a bumpy ride a couple of years ago, when environmentalists claimed its main mine was polluting local communities. An independent survey was carried out, Anglo Asian came out clean and calm has been restored, along with the dividend, which was suspended in 2024 and 2025.
Anglo Asian is unconventional. Four of the six board directors are in their 70s and 80s and have been in situ for years. Neither is Azerbaijan the most democratic of countries.
But management is well plugged in, succession plans are under discussion and, unlike almost any other miner, Anglo Asian has managed to bring its mines into production without recourse to shareholders.
With sales and profits expected to soar this year, and more to come in future, brokers believe Anglo Asian shares should rise to at least £5.50.
Cautious investors might choose to sell. Patient holders could yet reap more rewards from this maverick investment.
Traded on: Aim Ticker: AAZ Contact: angloasianmining.com
Many of my Midas tips have risen five-fold since I first recommended them.
These range from commodity producers such as precious metals group Hochschild Mining and palm oil producer MP Evans to ventilation firm Volution and defence giant BAE Systems.
Volution Group
Midas recommended Volution in 2014 when it had just floated on the stock market and the shares were £1.55. Today they are £6.65, and City followers believe they should exceed £8.50 over the next year or so.
Back in the early days, Volution generated most of its revenues from Vent-Axia fans for homes across the UK.
Under chief executive Ronnie George, the group has spread its wings, with sales equally split between here, continental Europe and Australasia.
There is a sizeable commercial division too, from schools and hospitals to offices, factories and, as of this year, copper and gold mines. Across the group, one theme prevails – healthy air at home and at work.
Regulations increasingly mandate that buildings are insulated but ventilated, and Volution products fit neatly within this theme.
Results last week showed real momentum with profits up more than 20 per cent to £112million and a dividend up 18.5 per cent to 12.8p. Further progress is expected, both organically and from acquisitions. That makes Volution an attractive investment for new and existing holders.
Traded on: Main market Ticker: FAN Contact: volutiongroupplc.com
BAE Systems
BAE Systems was an early tip, recommended in 2009 when the shares traded at just £3.87.
Today, they are £18.60, and were even higher earlier this year, topping £23. The performance since 2009 reflects a radical shift in attitudes towards defence as the world has become increasingly dangerous and national security has become a clear priority for sensible nations. But BAE has benefited from plenty of self-help measures too, as chief executive Charles Woodburn has focused on the so-called ‘three Ps’ – pension, portfolio and performance.
An onerous pension deficit has been addressed, the portfolio has been expanded and developed and a culture of hard work, drive and co-operation has helped to fuel a top performance.
Today, BAE sits on an order book of £84billion, a pipeline valued at around £180billion, a vast array of future opportunities and a central role in projects from the Global Combat Air Programme between the UK, Italy and Japan to the Royal Navy’s Dreadnought submarine fleet.
The company is justly proud of its high-tech, super-resilient drones and counter-drones, too – a key part of modern warfare.
BAE shares have come off their highs, as some investors have taken profits or fretted about the group’s lunch being eaten by smaller and nimbler competitors.
Those fears seem misplaced. At £18.60, with 22 years of rising dividends, the shares should deliver long-term value.
Traded on: Main market Ticker: BA Contact: baesystems.com
Looking back, one point stands out – the UK is home to a multitude of incredible businesses, world-beating know-how and incredible talent.

BAE Systems’ 120mm L44A1 LR weapon system on display in Bratislava, Slovakia
Raspberry Pi
The Cambridge-based computer specialist is a top example.
Primarily known for its low-cost kit used by schools and techno-geeks, Raspberry Pi is acquiring new fans, as its technology is increasingly used in industry, from military drones to ultrasound machines to display panels at Heathrow Airport.
Midas recommended the shares when it floated at £2.80 two years ago. Today, the price is £6.641.
Under super-charged chief executive Eben Upton, Raspberry Pi is winning business across the globe and, as more companies choose Raspberry Pi computers, interest in the company multiplies.
Half-year results last month showed soaring sales and profits, with brokers expecting more of the same for the full year and continued growth next year and beyond. Raspberry Pi shares have bounced around since floating in 2024 but the business is gaining traction and supporters believe the stock should top £10 in the next year or two.
Traded on: Main market Ticker: RPI Contact: raspberrypi.com

Primarily known for its low-cost kit used by schools and techno-geeks, Raspberry Pi is acquiring new fans
Bloomsbury
This publishing concern also punches above its weight on the worldwide stage. Known as the publisher of Harry Potter books and Sarah J Maas romantasy fare, Bloomsbury has defied the doomsters for years.
A £10,000 investment when the business floated in 1994 would be worth more than £610,000 today, if dividends had been reinvested – outgunning even Warren Buffett’s Berkshire Hathaway.
Midas came to the story much later, recommending the shares at £2.79 in 2020.
Even so, investors have done well, with the stock now at £6.73 and likely to head higher.
Founded by Nigel Newton in 1986, Bloomsbury differs from peers because it straddles consumer and academic publishing – from tomes, texts and online resources for education to an array of best-selling fiction.
Bloomsbury shares fell back earlier this year but have since recovered and should continue in that vein. Newton recently announced a well-received succession plan, the business is in fine fettle and figures this month are expected to please investors.
Shareholders who bought in 2020 may want to cash in some stock but, at £6.73, Bloomsbury still looks attractive.
Traded on: Main market Ticker: BMY Contact: bloomsbury-ir.co.uk
Losers and takeovers
Share-tipping is not easy. Over the years there has been the odd, horrible mistake, from which I have learnt valuable lessons.
Among the worst was MotifBio, a biotech business trying to develop a new antibiotic. The firm expected to gain regulatory approval in the US but its confidence was premature and the stock sank from 27p to less than a penny in a few months.
Sirius Minerals was an even sadder story. The business was hell-bent on building a transformative mine under the Yorkshire Moors to produce agricultural fertiliser. The plans were seductive but the project proved far too ambitious and shareholders lost out.
On the flip side, there have been some extraordinary wins.
Delivery specialist DX Group was tipped at 32p in July 2023 and acquired that November at 48.5p a share, delivering a 50 per cent return to investors.
And, of course, there was BG itself, tipped at £6.65 and then acquired by Shell Group ten years later in a deal initially valued at £13.50 a share.
Have you made or lost money from Midas share tips? Do tell us: money@mailonsunday.co.uk
DIY INVESTING PLATFORMS
AJ Bell
AJ Bell
Easy investing and ready-made portfolios
Hargreaves Lansdown
Hargreaves Lansdown
Free fund dealing and investment ideas
interactive investor
interactive investor
Flat-fee investing from £4.99 per month
Freetrade
Freetrade
Investing Isa now free on basic plan

Trading 212
Trading 212
Free share dealing and no account fee
Affiliate links: If you take out a product This is Money may earn a commission. These deals are chosen by our editorial team, as we think they are worth highlighting. This does not affect our editorial independence.
Compare the best investing account for you


