
The Bank of England has raised interest rates and signalled that a second increase could come before Christmas, warning that inflation may climb above 6 per cent.
The move will put further pressure on millions of borrowers. The Bank lifted its benchmark rate from 3.75 per cent to 4 per cent—the first increase in three years.
Governor Andrew Bailey also warned that, without clear evidence of an end to Donald Trump’s war with Iran, further rate rises could follow.
The decision is another setback for households already struggling with higher costs, while the Bank sharply reduced its projections for UK living standards.
Optimism that Mr Trump’s defeat in this week’s US midterm elections might help bring the Middle East conflict to an end has done little to improve the economic outlook.
Those hopes have nevertheless helped push oil prices below $100 a barrel.
But Mr Bailey said: ‘The whole situation is so volatile that you really don’t want to put much weight on two days which haven’t yet been backed by any firm evidence that there is a peace process which is going to lead to something concrete.’

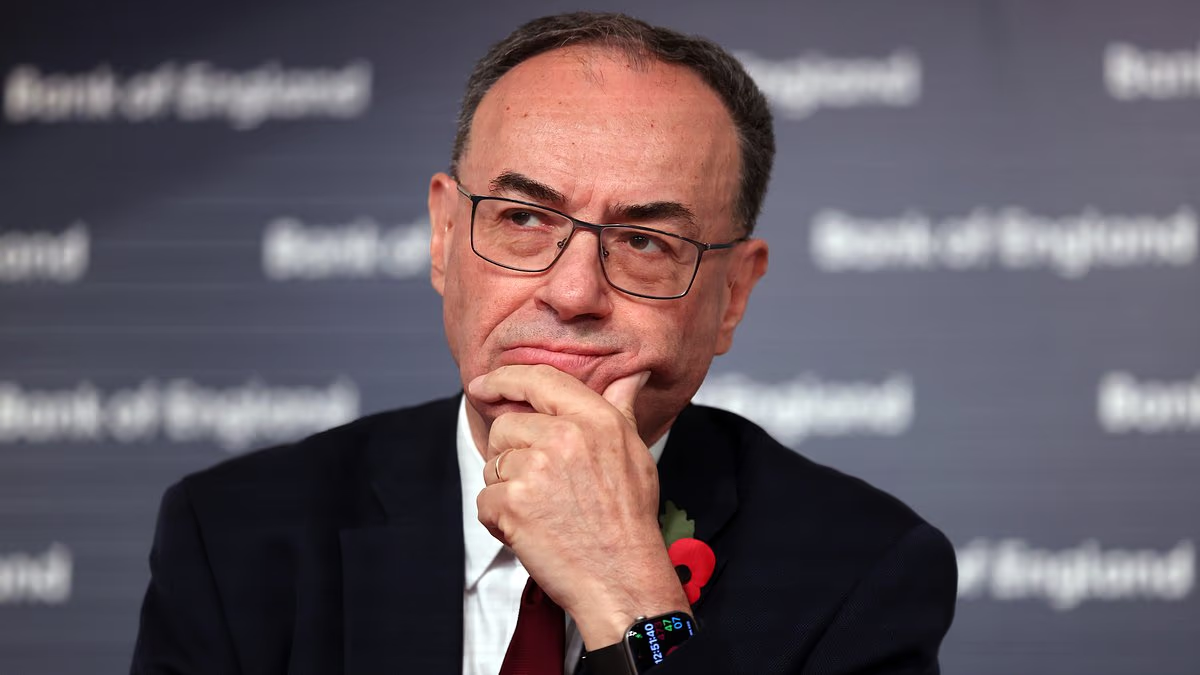
Bank of England governor Andrew Bailey warned that further interest rate rises could be necessary
He said the Bank would have ‘more information’ in the coming weeks, but added that the consequences would be considered at the MPC’s December meeting.
His remarks indicate that, unless meaningful progress is made towards ending the war, rates could rise again to 4.25 per cent when the Monetary Policy Committee meets eight days before Christmas.
Thursday’s increase, the first since August 2023, will immediately affect around one million borrowers with variable-rate mortgages. The average tracker mortgage will cost an extra £30.72 a month, while standard variable-rate customers face an average increase of £14.28.
For some families, that rise will effectively cancel out the £100 energy-bill support announced in the Budget.
More than seven million fixed-rate mortgage holders will not feel the impact straight away. However, 2.3 million of those borrowers have deals expiring by the end of 2027 and may face significantly higher repayments when they refinance.
A further December increase would add to the strain on households and the broader economy at a time when consumers would normally be preparing to spend more on Christmas gifts and celebrations.
The Bank has been pushed into action after Mr Trump’s war disrupted energy supplies from the Middle East, driving up oil and gas prices.
The resulting increase in petrol and diesel costs comes as typical annual energy bills are expected to rise above £2,000 from January.
Inflation has consequently risen to 3.5 per cent, its highest level in 11 months and well above the Bank’s 2 per cent target.
The Bank expects inflation to reach 4.9 per cent by next spring. Under an ‘adverse’ scenario in which the Iran conflict intensifies and oil reaches $130 a barrel, inflation could hit 6.2 per cent by the summer.
Until now, policymakers had held off raising rates in response to the conflict while assessing whether the energy shock would trigger ‘second-round’ effects, including higher prices for other goods and demands from workers for increased wages.
However, the Bank said the rise in oil and gas prices since the summer meant inflationary pressures ‘will be stronger and more persistent than previously expected’, making a rate increase necessary.
Mr Bailey said: ‘Today’s increase shouldn’t be seen as the first in an inevitable long sequence of hikes. But, unless the conflict in the Middle East is resolved, neither does it seem likely to be the last increase.’
The rate-setting MPC voted 8-1 in favour of a quarter-point increase. One member, Catherine Mann, supported a larger rise of half a percentage point.
In its updated forecasts, the Bank also warned that the outlook for living standards was deteriorating as inflation eroded workers’ incomes.
It expects post-tax labour income—a measure of living standards—to fall by 0.1 per cent in real terms this year. The decline is forecast to widen to 0.6 per cent next year.
A further interest rate rise within weeks could intensify the pressure.
Andrew Goodwin, chief UK economist at Oxford Economics, said: ‘December’s meeting now looks like a coin flip, with the path of oil and natural gas prices set to be the decisive factor.’
Chancellor John Healey said: ‘The Iran conflict is reaching deep into the pockets of families and businesses here at home.’


