
America’s debt crisis is intensifying as households face weak income growth alongside rapidly rising costs across the economy.
Household debt is nearing levels last recorded in the aftermath of the Great Recession, according to federal data released Friday.
The latest Federal Reserve Survey of Consumer Finances found that the proportion of American families falling behind on loan payments rose sharply to 20 percent in 2025, compared with 12 percent in 2022.
The share of families at least two months behind on their bills also climbed significantly. It surpassed eight percent, up from five percent in 2022, according to the survey, which is conducted every three years.
“Families were more likely to be behind on their financial obligations than at any point since the 2010 survey,” the Federal Reserve said.
Earlier Fed research documented the fallout from the Great Recession, the economic crisis that ran from December 2007 through June 2009. It was sparked by the collapse of the housing market and a severe stock market downturn, while unemployment eventually reached 10 percent.
Still, the latest report, covering the period from 2022 to 2025, presents a more complex picture of the financial pressures facing American households.
Although more families struggled to stay current on their bills, the wealth gap between richer and poorer households narrowed slightly.
The percentage of families using more than 40 percent of their income to cover debt payments also increased, reaching 8.6 percent from 6.5 percent in 2022. That was the highest level recorded since 2013.

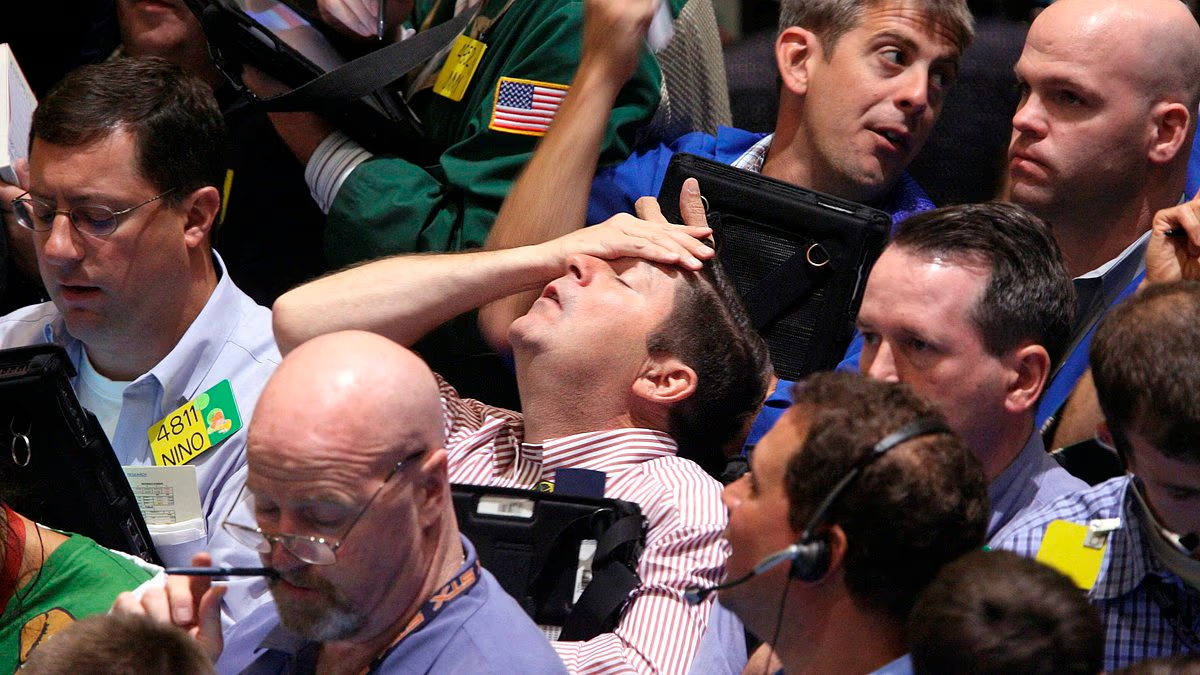
Federal Reserve data released Friday showed that Americans’ debt has reached levels not seen since the Great Recession, the economic crisis that lasted from December 2007 to June 2009 and followed the collapse of the housing market (pictured)
Average net worth, adjusted for inflation, rose seven percent to $1.24 million, the survey found.
However, median net worth—which offers a clearer picture of the typical American family—increased only two percent to $215,900. Larger gains among older and wealthier households helped push up the average.
Even that increase was relatively small compared with the previous survey period.
Family wealth jumped 37 percent from 2019 to 2022, marking the biggest increase in the survey’s more than 30-year history. Growth slowed substantially during the three years that followed.
MORE ON THIS: Saudi Arabia Faces Fresh Drone, Missile Strikes After Houthi Attacks
The divide between wealthy and lower-income households continued to expand as well. Median wealth among families in the top 10 percent of the income distribution surged 31 percent, while households in the bottom 40 percent saw their wealth decline.
Younger Americans experienced some of the sharpest setbacks. Families headed by someone under 35 saw median net worth fall 23 percent to $33,000 in 2025, down from 2022.
Older households, by contrast, continued to accumulate wealth. Families headed by someone aged 75 or older recorded a 37 percent increase in median net worth, bringing it to nearly $505,000.
The report said the only exceptions to the “general pattern” of rising median income were “Black non-Hispanic families, Asian families, and families toward the top of the usual income and net worth distribution.”

American families are contending with sluggish wealth growth, higher consumer costs and rising debt balances, leaving more households behind on their bills
For those families, “both median and mean income fell,” the report said.
Overall, inflation-adjusted median family income rose 7 percent to $82,200 between the surveys, while median net worth edged up just 2 percent to $215,900.
Average net worth rose 7 percent to $1.24 million, suggesting gains at the top helped lift the overall figure.
The Fed also found that the share of families carrying debt remained broadly unchanged at 77 percent, while median and average debt balances showed little movement from 2022.
The growing problem was the burden of keeping up with repayments, with more households devoting a substantial share of their income to servicing debt.
However, consumer spending has remained resilient. US household spending increased 6.1 percent in the 12 months through August – due partially to higher prices, but also a larger volume of purchases, according to the Department of Commerce.
Despite these numbers, young Americans appear to be caught in a financial bind. Gen Z is carrying more credit card debt while increasingly turning to buy now, pay later services, even as many hope to build wealth by investing in stocks, according to a new Deloitte survey.
The share of Gen Z borrowers carrying credit card balances for more than a month rose nearly 20 percent between the third quarter of 2023 and the second quarter of 2026, while the figure declined among other generations.
Use of buy now, pay later services among Gen Z also surged to 22.8 percent in the first quarter of 2026, the highest level among generations tracked by Deloitte over three years, before easing to 17.6 percent in the following quarter.